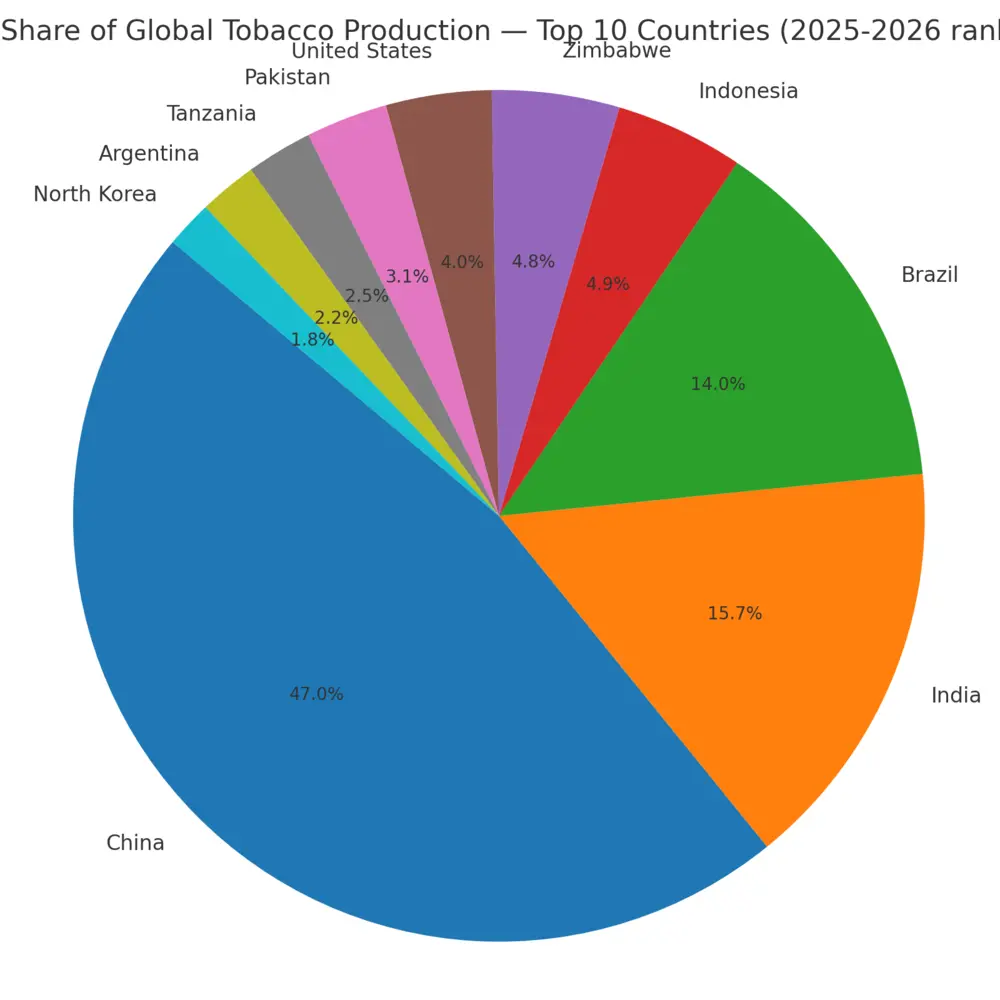
Top 10 Tobacco Producing Countries: Global Production Rankings, Percent Shares and Insights
0
(0)
Have you ever asked which countries hold the most leverage over global natural rubber exports and what that means for pricing, procurement, and supply security? The period 2025 to 2026 shows a concentrated group of exporters that shape global trade flows for tires, medical products, and industrial goods. This report offers an authoritative ranking of the top 10 rubber exporting countries by export value, explains why each country matters to exporters and buyers, and highlights practical trade implications for procurement teams and policy makers. The data reflect export-value rankings rather than raw production alone, because value better captures processing, quality, and the commercial importance of exports to global markets.
What this ranking captures and why value-based export rankings matter
This ranking emphasizes export value in US dollars to reveal which countries capture more of the downstream revenue from rubber commerce. Export-value rankings show where processing, grading, and logistics add commercial worth; they are therefore more relevant for importers negotiating contracts and for analysts modeling trade exposure. A country that exports higher-value, graded rubber or semi-processed sheets may rank above a higher-volume raw producer in value-based lists. These dynamics have direct consequences for supply risk, pricing volatility, and contract strategy for buyers in China, Europe, and North America.
1. Thailand (approximately 31.2% of export value)
Thailand remains the premier exporter of natural rubber and accounts for roughly one third of global export revenue, making it the single most influential nation for global rubber trade. The country benefits from a long-established smallholder network, modern processing hubs, and efficient port connections that facilitate exports to major demand centers in East Asia and Europe. Thailand’s ability to export graded and semi-processed rubber rather than raw latex gives it a pricing edge that influences global benchmarks. Seasonal weather and domestic policy can temporarily constrict shipments, and when that happens, global market prices react rapidly. For procurement teams seeking volume security and reliable contract terms, Thailand is often the best first call, but buyers should pair Thai contracts with secondary suppliers to reduce concentration risk.
2. Indonesia (18.3% of export value)
Indonesia stands as a leading large-scale exporter that combines sizeable plantation acreage with a growing processing industry that supplies both raw and processed rubber to global buyers. Indonesia’s scale helps stabilize volumes for importers, but the export mix between raw and processed shipments can cause price variability. The government and private sector are investing in traceability and certification programs that target buyers who require sustainability verification for procurement tenders. For firms seeking the best balance between volume and emerging compliance standards, Indonesia is a strategic supplier to include in multi-source contracts. Its role in the global rubber export market means shifts in Indonesian export policy or logistics capacity will have measurable effects on global trade flows.
3. Côte d’Ivoire (approximately 15.5% of export value)
Côte d’Ivoire ranks among the finest examples of West Africa’s rising role in natural rubber exports and now contributes a large share of global export value. Rapid plantation investments, favorable export policies, and strong buyer relationships have enabled Ivory Coast to capture significant downstream export revenue. This country’s emergence has rebalanced some trade routes, with more rubber moving directly from West Africa to European and Asian processing hubs. For corporate procurement managers, adding Côte d’Ivoire contracts is an optimal diversification strategy to mitigate dependence on Southeast Asian suppliers. Continued investments in processing capacity and certification would further increase its export value and commercial importance.
4. Vietnam (around 8% of export value)
Vietnam has steadily improved export value through industrial upgrading and clustering of processors that convert raw latex into higher-value grades and semi-finished components. Its ability to capture more downstream revenue without the largest plantation area makes Vietnam one of the most efficient value-capture stories in the sector. East Asia and European buyers increasingly source technical-grade rubber from Vietnam because of consistent quality and competitive pricing. For buyers who need consistent grading and reliable delivery, Vietnam can be among the top choices alongside major Southeast Asian suppliers. The country’s increasing export sophistication also helps it command premium contracts for certain specialized grades.
Malaysia remains a legacy exporter that has shifted toward higher-spec rubber types for industrial applications, supported by domestic R&D and a midstream chemicals industry. The country’s historical depth in rubber research and industrial compounding gives it a comparative advantage for buyers seeking technical consistency and regulatory compliance. Malaysia’s exports often include specialized grades that serve construction, automotive, and industrial clients who require exacting specifications. When supply contracts prioritize quality and regulatory traceability, Malaysia ranks among the finest supplier options. For supply-chain strategists, Malaysian exports represent quality-focused sourcing rather than pure volume.
6. Cambodia (Est. 3.7% of export value)
Cambodia’s export footprint grew quickly as plantation development and foreign investment scaled production for export markets. Cambodia offers competitive pricing due to lower land and labor costs, and exporters have attracted processors seeking alternative sources. However, Cambodia still needs more consistent grading, certification systems, and logistics maturity to match the top exporters on quality metrics. For buyers looking for cost-effective supplementary volumes or spot-market hedges, Cambodia presents value, but risk controls and quality checks are essential. The nation’s upside depends on continued investments to professionalize exporters and to meet demanding purchaser standards.
7. Laos (Est. 2.5% of export value)
Laos functions as a strategic regional supplier that complements larger exporters and feeds processors across Southeast Asia. Its export growth results from new yields and cross-border trade arrangements that improve export corridors to Thailand and Vietnam. Laos is often useful as a secondary source for traders needing quick additional volumes during peak demand, but its small scale and developing processing base mean buyers should treat Lao contracts as supplementary to larger primary suppliers. For corporate buyers seeking diversified sourcing, Laos offers practical value as part of a multi-country procurement plan.
8. Belgium (Est. 2.5% of export value)
Belgium appears on export lists because it functions as a European processing and re-export hub rather than a raw material producer. Belgian ports and chemical processing facilities import raw rubber and export processed compounds to EU manufacturers, which is reflected in export-value statistics. This role highlights a key trade insight: export leadership can reflect value-added processing and trade intermediation rather than plantation acreage alone. For EU buyers, sourcing from Belgian processors can deliver top-grade consistency and compliance but may come at a higher landed cost. Belgium’s position underscores the importance of trade logistics and midstream processing for global rubber export statistics.
9. Ghana (Est. 1.4% of export value)
Ghana’s emergence on the export list is notable for West Africa’s expanding role in rubber exports. Plantation investments and partnerships with Asian processors are driving export growth, and Ghana has become an attractive complementary supplier for buyers who want to spread country risk. While Ghana’s export volume is smaller than the largest producers, it offers diversification and seasonal arbitrage opportunities for traders. Upgrading processing and meeting certification standards will help Ghana capture higher export value as global buyers prioritize sustainability and traceability. For risk-aware procurement teams, Ghana can be part of a balanced sourcing strategy that includes premier suppliers and emerging markets.
Myanmar supplies modest but potentially volatile export volumes, and its export share reflects both agronomic potential and geopolitical risk. When political and logistical conditions permit stable shipments, Myanmar can contribute meaningful volumes to regional supply chains. However, ethical sourcing concerns, certification requirements, and delivery reliability must be evaluated carefully. Buyers should treat Myanmar as a contingent source that can complement larger suppliers when due diligence and traceability are assured. For those seeking additional capacity during tight markets, Myanmar may offer value, but it is not typically a primary long-term contract destination for large, risk-averse buyers.
Uses of Tobacco
Tobacco competes with rubber for arable land and farm labor in several countries, affecting long-term rubber acreage.
Where farmers can switch between tobacco and rubber, short-term incentives or tax policies that favor tobacco can reduce new rubber planting and thus future export capacity.
Programs that encourage perennial crops like rubber over seasonal tobacco can stabilize rubber supply over multiple years, but they require targeted financing and farmer training.
For procurement teams, understanding tobacco-to-rubber land-use substitution explains potential supply constraints and allows better risk management in contract planning.
Policy-driven reductions in tobacco cultivation have historically led to increases in perennial plantation crops, which is relevant for medium-term export forecasts.
Market context and trade implications for 2025 to 2026
Global rubber export value remains concentrated among a handful of countries, which increases the sensitivity of prices to climatic events, labor shifts, and policy changes in core exporters. The combined export value of Thailand and Indonesia represents a dominant portion of the market, and supply interruptions in either country ripple through global pricing. Importers should therefore prioritize multi-sourcing, build flexibility into contracts with price adjustment mechanisms, and require supplier audits and sustainability verification to reduce exposure. Freight costs, tariff changes, and buyer procurement policies will materially affect landed costs and export receipts for 2026 contracts. Strategic buyers aiming for the best risk-adjusted sourcing should balance the leading exporters with rising West African suppliers.
Conclusion
The global natural rubber export landscape for 2025 to 2026 remains highly concentrated yet shifting: Thailand and Indonesia exert major influence on export value and prices, Côte d’Ivoire and Vietnam are among the rising exporters capturing more downstream revenue, and smaller exporters and processing hubs play important complementary roles. For procurement and trade professionals, the most effective strategies will be multi-sourcing, enforcement of traceability and certification, and flexible contracting that balances cost with supply resilience and sustainability. The best commercial outcomes will come from blending volume security, quality assurance, and responsible sourcing.